The 457(b) “Cheat Code” for Early Retirees
If you want to retire before 59½, one of the most useful accounts you can have is also one of
The 457(b) “Cheat Code” for Early Retirees Read Post »
If you want to retire before 59½, one of the most useful accounts you can have is also one of
The 457(b) “Cheat Code” for Early Retirees Read Post »
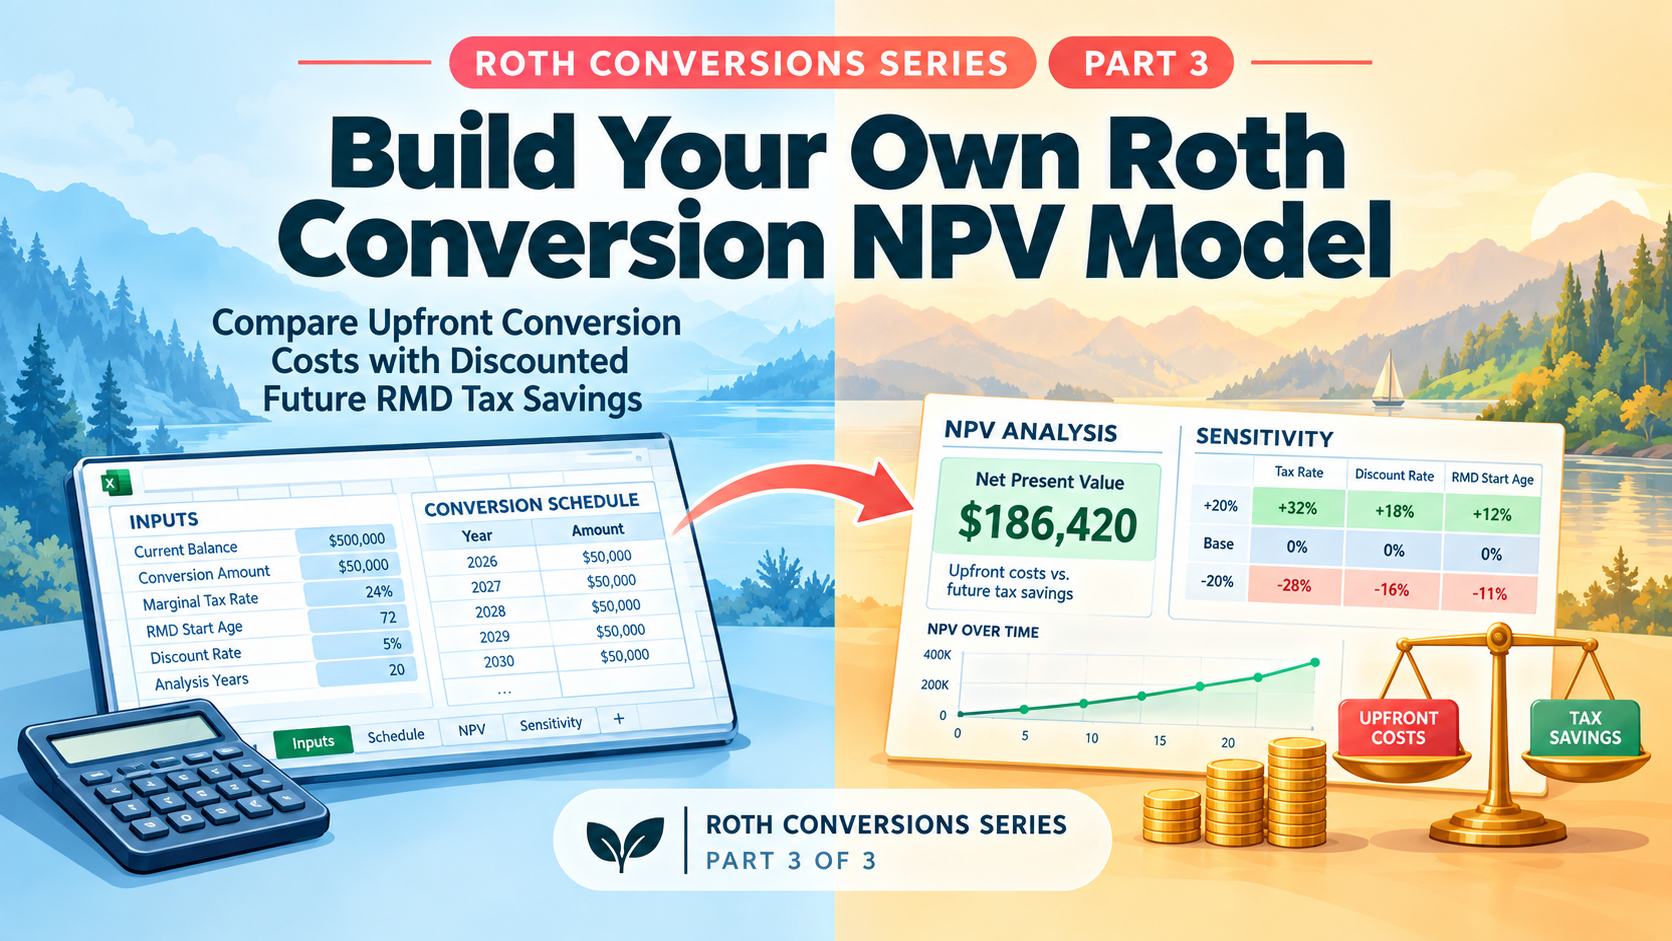
This is Part 3 in a series on Roth conversions. If you haven’t read Part 1 and Part 2, you
Part 3: Build Your Own Roth Conversion NPV Model Read Post »
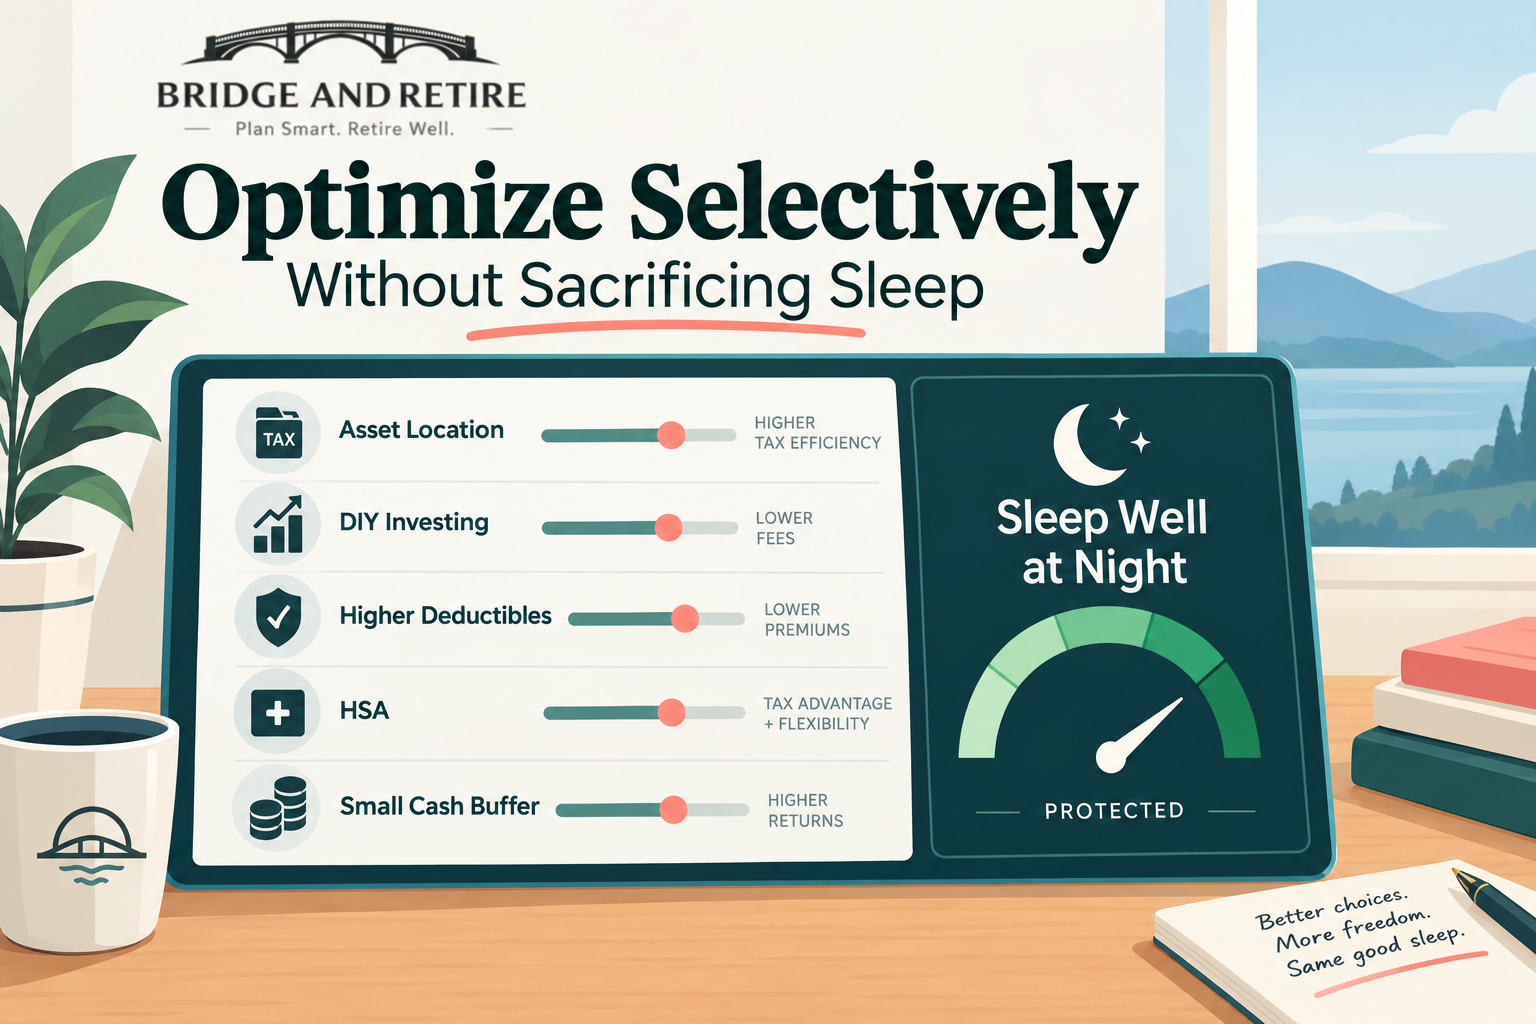
In a recent post, I listed five things I choose not to optimize in favor of sleeping well at night
Five Things I Do Choose to Optimize (Even Though I Value Sleep) Read Post »
When people think about financial risk, they are usually picturing market volatility. They worry about a concentrated stock position that
The Risks Nobody Talks About: Fraud, Fees, and Financial Decisions as You Age Read Post »
Part 1: When Should You Do Roth Conversions and Why do Most Calculators Get the Analysis Wrong? There is no
Roth Conversions Using a Discounted Cash Flows (DCF) Framework Read Post »
Rebalancing triggers taxes if you’re not careful. Here’s a framework for rebalancing across taxable, pre-tax, and Roth accounts without the tax hit.
Locked out of a Roth IRA because of your income? Learn how the Backdoor Roth works, when it makes sense, and how to avoid common tax mistakes.
Backdoor Roth 101: What It Is, Who Needs It, and Where It Breaks Read Post »
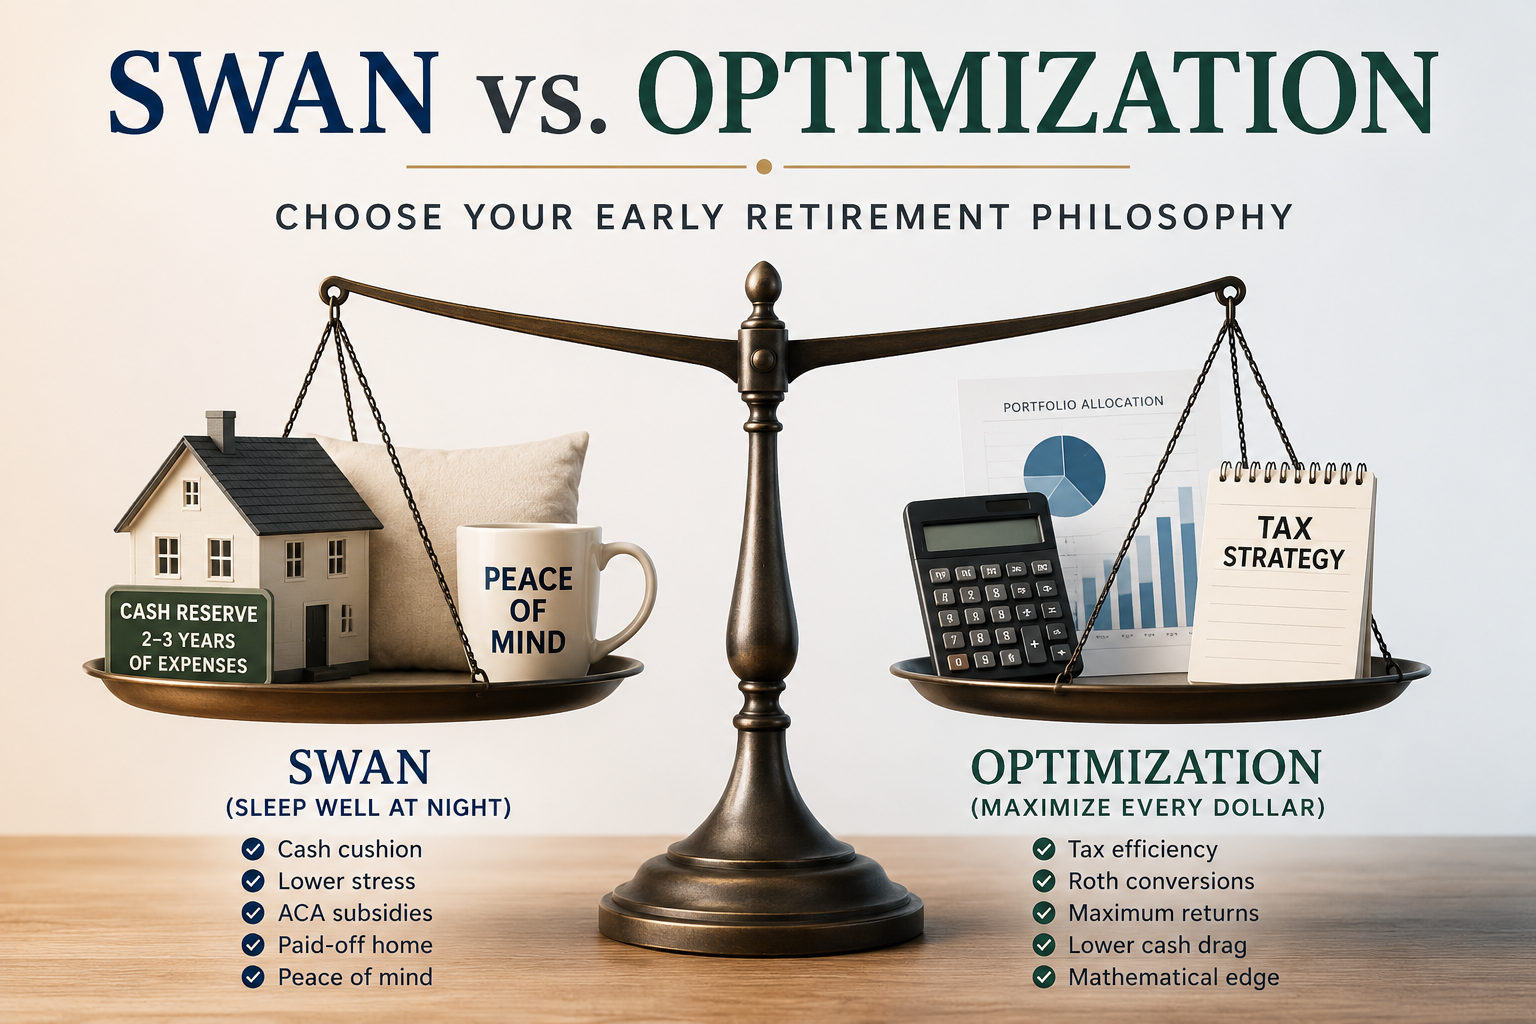
Should you maximize every dollar or maximize your peace of mind? This post looks at the fundamental clash between financial optimization and the “Sleep Well At Night” (SWAN) philosophy across cash buffers, Roth conversions, college savings, and paying off a mortgage early.
Sleeping Well at Night (SWAN) vs. Optimization: Choose Your Early Retirement Philosophy Read Post »
Standard financial education teaches us how to build wealth, but completely ignores how to defend it. When dealing with high-pressure wealth managers and complex products, survival requires mastering one crucial skill: looking a pro in the eye and realizing “No” is a complete sentence.
No is a Complete Sentence: Playing Financial Defense Against Financial Pros Read Post »
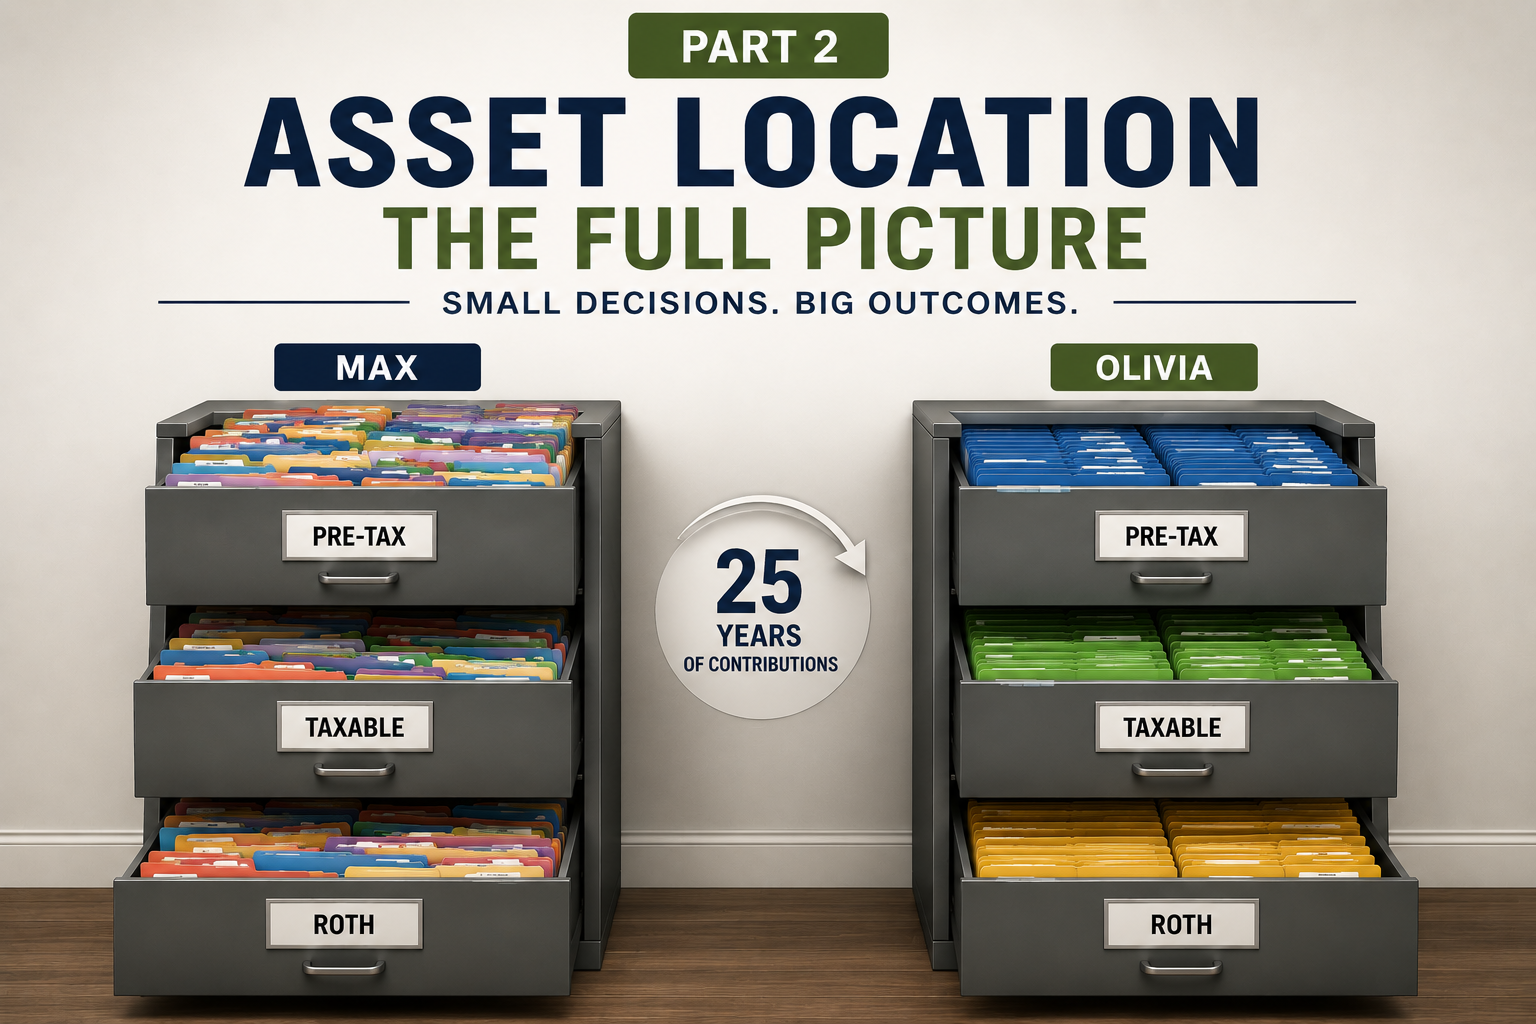
Does asset location actually matter? In Part 2, we add a realistic wrinkle to the math: ongoing contributions. Find out how a simple organizational tweak can save over $76,000 in retirement taxes, why a smaller pre-tax balance is secretly awesome, and why you officially have permission to ignore all of it if you want to.
Part 2: Does Asset Location Actually Matter? Read Post »